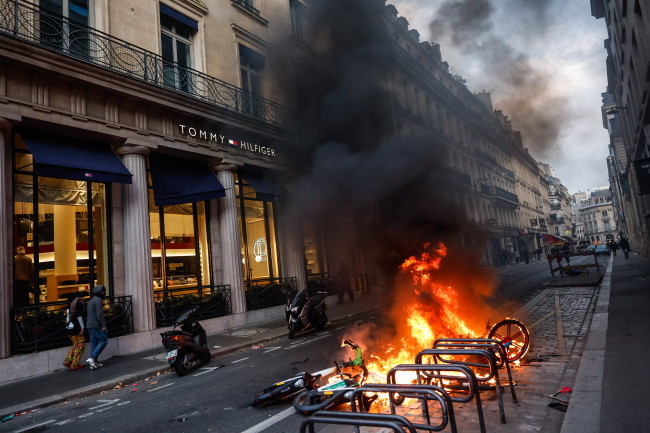


Riots that broke out during protests over social issues have taken France by surprise, briefly overshadowing the debate over the 2027 budget. The budget was meant to be a step toward repairing public finances. Markets and financial institutions are uneasy about how the situation will develop, with a presidential election on the horizon.
In September 2025, then-Prime Minister François Bayrou addressed parliament, which soon afterward passed a vote of no confidence against him, forcing the government to resign. In his speech, Bayrou spoke about rising public debt, which costs France more and more. “Our country works, believes it is getting richer, but over all these years it has been getting poorer,” the politician warned, comparing this gradual impoverishment to a “silent and invisible hemorrhage.”
At that time, France’s public debt stood at 114% of GDP, and the austerity budget proposed by Bayrou, which lawmakers rejected, envisioned cuts of 44 billion euros. A year later, the government of current Prime Minister Sébastien Lecornu is proposing cuts of 43 billion euros in the 2027 budget. Public debt has now risen to 119% of GDP and is expected to reach 121.7% of GDP in 2027. The situation is unprecedented, because France has recorded higher debt – more than 300% of GDP – only in 1946, when World War II ended.
The roots of the current problems go back a long way. Since the mid-1970s, France has run budget deficits, with spending exceeding revenue, and public debt has been rising since the 1990s. The Covid-19 pandemic further damaged France’s finances – President Emmanuel Macron opted for a “whatever it costs” strategy to support French businesses during lockdown. It helped the economy, but public debt crossed the symbolic threshold of 100% of GDP.
As the daily Le Monde recently noted, experts do not agree on the maximum level of debt that should not be exceeded. A state’s ability to borrow depends above all on the confidence of the markets and on its situation relative to other countries. “We have the confidence of the markets in the sense that we have no problem issuing debt,” Finance Minister Roland Lescure argued on Oct. 14 on Franceinfo radio. He acknowledged, however, that it is an “alarm signal” that debt costs France more and more.
What weighs on France more and more heavily is the interest paid to creditors. Minister Lescure told the Senate finance committee on Oct. 9 that interest payments will reach 91 billion euros in 2027 and could reach 100 billion euros before 2030. It will now be the largest item in the state budget, ahead of spending on education and defense.
The yield on French bonds has also been rising in recent months, reaching 5.11% on Thursday – the highest since 2002. Investors are watching the spread, the difference between the yields on French and German bonds. Germany is Europe’s most solid debtor, so the spread serves as an indicator of investor confidence. On Thursday it exceeded 173 basis points, the widest since November 2011.
Another warning sign may be the decision by the rating agency Moody’s on France’s rating, expected Friday evening. The current rating is Aa3 (high, but the lowest in the elite Aa group), with a negative outlook.
On Oct. 14, International Monetary Fund Managing Director Kristalina Georgieva, when asked about France, cautioned that for now Paris is trying to adopt a budget that would reduce the deficit, but stressed that restoring investor confidence “takes time.”
Meanwhile, in the National Assembly, the lower house of the French parliament, the budget debate has been suspended until Oct. 27, and no compromise is in sight. So far, deputies have submitted about 2,500 amendments, which, Budget Minister David Amiel warned, would deepen the budget deficit by 10 billion euros.
Lecornu’s minority government may take the same route as a year ago – forcing the budget through by using a mechanism that allows bills to be adopted without a vote, which, however, carries the risk of a no-confidence vote. There is also a procedure, never before used, for putting the budget into effect by ordinance (a legal act with the force of law, issued by the executive branch) if parliament does not rule on the draft within 70 days.
A presidential election will be held in France in the spring of 2027, and some candidates have presented their ideas for tackling debt and the deficit. The polling favorite is far-right leader Marine Le Pen, who has promised to bring the deficit below 3% of GDP by 2030 and to reduce debt to 112% of GDP by 2032 (the end of a five-year presidential term). Among the ways of finding savings, Le Pen proposes, among other things, reducing France’s contribution to the European Union budget, which would bring in from 9 billion to 14 billion euros in individual years.
Le Pen cites the need to fight debt, and the fact that the country is “on the verge of insolvency,” as justification for her intention to halt financial aid to Ukraine. “After I am elected, we would maintain aid for six months so as not to back anyone into a corner. But then we will halt financial aid to Ukraine, because we no longer have the means for it,” the politician warned in an October interview with Dutch-language broadcaster VRT News.
From Paris, Anna Wróbel (PAP)